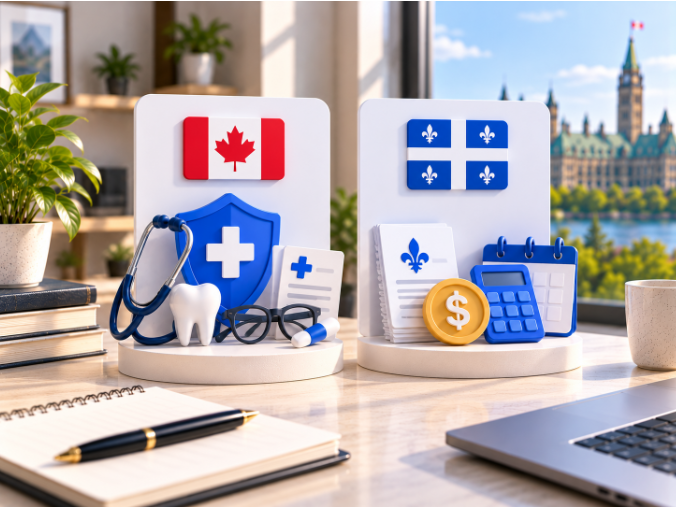
A health spending account that works smoothly in Ontario or Alberta can create extra payroll work in Quebec. The reason is that the federal government and Quebec apply their own tax rules to the same employer-paid benefit. This guide explains the federal rule, what is different in Quebec, why Quebec’s benefits landscape looks different in the first place, and what employers with Quebec staff should check before they launch a plan.
Key Takeaways
- The CRA says medical expenses paid under a qualifying private health services plan (PHSP) are not taxable, and payments outside a PHSP are generally taxable.
- Revenu Québec treats employer contributions under a group insurance plan, including a PHSP, as a taxable benefit for the employee.
- The same benefit can therefore be non-taxable federally and taxable in Quebec.
- Quebec had the lowest workplace medical or dental coverage rate of any province in 2024, at 60.6%.
- Confirm reporting and withholding with your payroll provider or accountant.
How Does the Federal Rule Work?
The CRA’s page on medical expenses and private health services plans says that if an employer pays or reimburses an employee’s medical expenses, the payment is generally a taxable benefit, but medical expenses paid under the terms of a PHSP are not. A plan counts as a PHSP when it covers only medical and connected expenses, when 90% or more of premiums or benefits relate to expenses eligible for the medical expense tax credit, when it is in the nature of insurance, and when it covers only the employee and certain family and household members. The CRA’s page on private health services plan premiums adds that when an employer makes contributions to a PHSP for employees, there is no taxable benefit for the employees.
What Is Different in Quebec?
Revenu Québec takes a different approach. Its page on contributions to a group insurance plan, including a private health services plan says that contributions or premiums an employer pays under a group insurance plan for an employee’s coverage constitute a taxable benefit for the employee, and it lists a private health services plan as one type of group insurance plan. The employer includes the value of the benefit in boxes A and J of the employee’s RL-1 slip for coverage under a PHSP.
In practice, the same contribution can be non-taxable under the federal rule and taxable for Quebec income tax purposes. The Treasury Board of Canada Secretariat describes the same principle for federal public service plans, noting that employer contributions towards certain group insurance plans are considered a taxable benefit for employees who reside in Quebec.
Why Does Quebec’s Benefits Landscape Look Different?
Statistics Canada’s 2025 report on medical and dental benefits coverage found that, in 2024, Quebec (60.6%) was among the provinces with the lowest rates of workplace medical or dental coverage for employees, compared with 71.7% in Saskatchewan and 70.0% in British Columbia. It suggests this may be due to Quebec’s public health insurance framework: Quebec requires all residents to have prescription drug insurance, either through a private plan or through the Régie de l’assurance maladie du Québec, which may reduce the need for employers to offer supplementary benefits. For employers, that can make flexible, targeted accounts attractive, but it also means Quebec employees may have different baseline coverage from colleagues elsewhere.
Federal and Quebec Treatment Side by Side
| Question | Federal (CRA) | Quebec (Revenu Québec) |
| Employer-paid benefit under a qualifying PHSP | Not taxable to the employee | Taxable benefit for Quebec income tax |
| How it is reported | Not reported as a taxable benefit | Included in boxes A and J of the RL-1 |
| Payments outside a PHSP, such as general reimbursements | Generally taxable | Check Revenu Québec’s list of taxable benefits |
A Practical Checklist for Employers With Quebec Staff
- Identify which employees live in Quebec, since the provincial rule follows the employee.
- Ask your payroll provider how it handles provincial taxable benefits and RL-1 reporting.
- Ask your plan administrator for the contribution or benefit amounts you will need at year-end.
- Decide whether the plan covers dependants and how to document it.
- Review the arrangement each year with your accountant, since rules and plan design can change.
How Can an Administrator Help?
Look for reports you can pull whenever payroll asks. GoKlaim HSA page confirms admins and employers can download expense reports in real time for any given dates through the admin platform, and its homepage adds monthly reports on allowance usage for employers and employees. The site is available in English and French, and an HR consultant quoted there calls the service a Quebec-based solution for small businesses. Payroll treatment remains the employer’s responsibility, so confirm your approach with a professional.
Final Thoughts
For employers with staff in more than one province, the lesson is to treat Quebec as its own case. The federal rule on private health services plans is generous, but Revenu Québec does not mirror it, and the difference shows up in payroll. Plan for it before you launch: identify Quebec employees, align your payroll provider and plan administrator, and agree who produces which numbers and when. Then keep the documentation simple and consistent from year to year. A few hours of preparation at the start is easier than a correction at tax time, and it lets employees enjoy the benefit without surprises.
Frequently Asked Questions
Is a health spending account taxable in Quebec?
The benefit is not taxable federally if the plan is a qualifying PHSP, but Revenu Québec treats employer contributions under a group insurance plan, including a PHSP, as a taxable benefit for Quebec income tax.
Where is the benefit reported in Quebec?
Revenu Québec says the value goes in boxes A and J of the employee’s RL-1 slip for coverage under a private health services plan.
Does the rule apply to employees who work remotely from Quebec?
The provincial rule follows where the employee lives and is taxed, so check with your payroll provider.
Do WSA benefits follow the same rules?
Not necessarily. The CRA treats benefits and allowances outside a PHSP as generally taxable, and Quebec has its own taxable benefit rules, so review each category.