There is a category of insurance mistake that is particularly expensive: the one you do not discover until after the loss. In Saskatchewan, acreage and farm properties generate a disproportionate share of these moments because the insurance questions they raise are genuinely more complex than those of a standard urban home, the coverage gaps are larger, and the people living on these properties often do not realise how their policy treats the land, the structures, the equipment and the activities on it until something goes wrong.
This is not a criticism of property owners. The insurance market for acreages and farm properties is legitimately complicated, and the assumptions that work perfectly well for a city home do not always translate. Understanding where the gaps typically appear is the most practical thing a rural homeowner can do before they need to make a claim.
Assuming a standard home insurance policy covers everything on the property
The most widespread misconception is that a standard home insurance policy provides the same coverage across an acreage as it would on a city lot. It does not. Standard residential policies are designed around a single primary dwelling on a relatively small lot, and while they include some coverage for detached structures, that coverage has both dollar limits and exclusions that can leave significant assets uncovered.
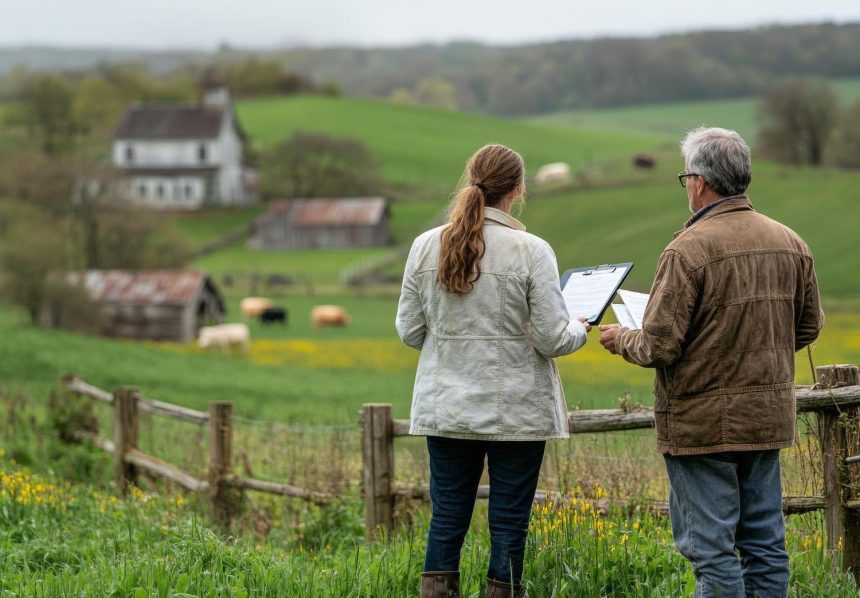
An acreage homeowner served by brokers like Cooke Insurance in Saskatoon often discovers that their outbuildings, including machine sheds, heated shops, hay storage buildings, old granaries and other secondary structures, fall into a coverage category that has a combined limit often set at a percentage of the main dwelling coverage. If the combined replacement value of those structures exceeds that limit, the difference is uninsured. On a property with a significant heated shop or a purpose-built barn, that gap can be substantial.
The solution is not necessarily a farm policy. It is a thorough review of what is on the property, the replacement cost of each structure, and how the current policy treats it. Some structures may qualify for endorsements that increase their coverage. Others may require a separate policy component or a different policy altogether.
Misunderstanding how equipment and machinery is covered
Equipment coverage is one of the most varied and frequently misunderstood elements of rural property insurance. A standard home policy does not cover farm equipment, agricultural machinery or equipment used in any commercial activity on the property. A garden tractor used for personal lawn maintenance sits in a different coverage category than a tractor used for hay production, even on the same property.
For acreage owners who use their property for any form of agricultural activity, even small-scale, understanding how their equipment is classified is important. Is it recreational? Is it incidental to personal land management? Is it used to produce income? These distinctions affect whether equipment is covered, whether it requires a separate rider or a farm policy, and how a claim would be evaluated.
Additionally, older equipment and machinery is often subject to actual cash value rather than replacement cost valuation in standard policies. The distinction matters significantly for older tractors or specialty equipment where replacement cost substantially exceeds market value.
Underestimating the replacement cost of outbuildings
Saskatchewan’s construction costs have increased meaningfully over the past several years. A heated shop or outbuilding that was insured at a value established five or six years ago may be significantly underinsured at current replacement costs. This is an issue across all property types, but it is more acute for rural properties because the structures involved are often larger, more specialised and more expensive to rebuild than standard residential outbuildings.
Replacement cost assessments should reflect current construction costs, including materials, labour and the specific features of the structure. A building with concrete floors, in-floor heating, upgraded electrical and a specific structural design is not interchangeable with a basic agricultural shed, and the insurance coverage should reflect that difference. Periodic appraisals or reviews with a broker familiar with current construction costs in the region can catch underinsurance before it becomes a problem.
Not understanding how income-generating activities affect coverage
Many acreage owners operate some form of income-generating activity on their property, whether that is boarding horses, a small grain operation, selling produce, operating a home-based business or renting out part of the property. Each of these activities can affect both the type of insurance required and the validity of a standard home policy claim.
Most standard home insurance policies have explicit exclusions for business activities conducted on the property. If a fire occurs in a building used for commercial purposes, and the policy excludes commercial activity, the claim may be denied or significantly limited. This is not a theoretical risk. It is among the more common coverage disputes in rural property insurance.
Agricultural operations of any meaningful scale typically require a farm policy rather than a home policy, or at minimum a commercial endorsement that specifically addresses the farming activity. The definition of what constitutes a farm operation for insurance purposes varies by insurer and policy, which is one of the reasons that working with a broker who regularly handles Saskatchewan farm files matters. The broker who regularly writes coverage for mixed acreage properties understands the nuances that a generalist might miss.
What happens with neighbours, fences and shared access
Saskatchewan acreage properties often involve shared fencing, road access agreements, water rights questions and boundary situations that have been informally managed for generations. When a dispute arises, or when a loss affects property or equipment that sits near a boundary, the question of which insurance applies can become complicated.
Liability coverage on an acreage or farm property should be reviewed specifically for situations where guests, visitors, contractors or neighbouring landowners might be affected by conditions on the property. A standard liability limit appropriate for an urban home may be insufficient for a rural property where the range of potential incidents is wider.
The SGI context and what it means for Saskatchewan buyers
Saskatchewan operates through a provincial auto insurance system under the Saskatchewan Government Insurance framework, and SGI-authorised brokers like Cooke Insurance handle both provincial auto and the private insurance lines including home and farm. Understanding how the provincial and private insurance markets interact in Saskatchewan, and what an SGI broker can offer versus what requires a private insurer, is part of the practical landscape of buying insurance in this province. Farm and acreage properties frequently require a combination of products that a full-service brokerage can coordinate under one relationship.
The Insurance Bureau of Canada and understanding your rights
The Insurance Bureau of Canada (IBC) provides consumer resources for understanding property insurance rights and responsibilities, including guidance on the claims process, how replacement cost coverage works, and what recourse is available to homeowners who believe a claim has been handled incorrectly. For rural homeowners navigating the complexity of acreage or farm insurance, IBC’s consumer resources are a useful supplement to conversations with a broker.
The practical step that prevents most of these problems
The most effective way to avoid coverage gaps on a Saskatchewan acreage or farm property is a detailed policy review that itemises every structure on the property, its current replacement cost, how it is used, and how the current policy treats it. For properties with equipment, livestock, income-generating activities or any ambiguity about land use, that review should specifically address each of those elements.
This is not a complex or expensive process. A conversation with a broker who regularly handles rural Saskatchewan files, one who has seen the range of situations these properties create at claim time, takes an hour and produces a clear picture of what is covered, what is not and what can be added. That hour is considerably less expensive than discovering the gaps after a fire, flood or liability claim.
The properties that generate the most difficult claim conversations are almost always ones where the coverage was last reviewed at the point of purchase and has not been revisited since. The structures, equipment, activities and land use on an acreage change over time. The insurance should change with them.